
Tokenised Stocks
Why Tokenised Stock Prices Differ From the Real Share Price
Tokenised equities trade 24/7 but the underlying market does not, and retail cannot arbitrage the gap. Where drift comes from, when it is worst, when a discount is information rather than noise, and how to avoid trading into it.

The pitch for tokenised equities is 24/7 trading. The consequence nobody leads with is that the underlying market is open about 32 hours a week, and your token trades 168.
For the other 136 hours, there is no reference price. There is only what buyers and sellers in a comparatively thin order book think the reference price will be when the market reopens.
That gap is where drift lives. Drift is not a defect in these products; it is an unavoidable result of wrapping a part-time asset in a full-time instrument. But it is the most common way retail holders of tokenised equities lose money without ever being wrong about the company, so it is worth understanding precisely.
The three sources of drift
1. Closed-market price discovery
When US markets close on Friday afternoon, the last printed price for Nvidia is a fact. By Sunday evening it is a 48-hour-old fact, and the token has been trading against nothing but opinion the entire time.
If meaningful news lands Saturday morning, the token price moves. It has to; that is the feature. But it moves on the judgement of whoever is awake and willing to quote, in a market with a fraction of weekday depth. Sometimes that judgement is excellent. Sometimes Monday's open makes it look ridiculous.
This is not mispricing in any exploitable sense. It is genuine uncertainty about an unobservable value, and it is widest exactly when you most want to trade.
2. Arbitrage that is closed to you
In a normal market, price gaps close because someone profits by closing them. For tokenised equities, that mechanism exists but you are not part of it.
Recall the redemption reality from what you own: xStocks redemption sits with the issuer's institutional channel, not retail. Ondo processes redemptions only for onboarded, eligible holders. For most bStocks holders outside the ADGM, access is secondary-market only.
The arbitrage that keeps a token pinned to its underlying — buy the cheap side, redeem or create, capture the spread — is an institutional activity. When the institutional participants are active and well-capitalised, drift stays tight. When they step back, drift widens, and nothing you can do closes it.
This is the key asymmetry. An ETF holds close to NAV because authorised participants arbitrage it continuously in size. A tokenised stock holds close to its share price under the same logic, but with a much smaller, less committed set of participants and more operational friction. Similar mechanism, weaker spring.
3. Order-book depth
Headline numbers describe platforms, not tickers. A platform can hold $900 million in tokenised equities and still have a thin book in the specific name you want at the hour you want it.
Depth varies by:
- Ticker. Tesla and Nvidia have real books. The tenth-most-popular name does not.
- Hour. Weekday US hours are best, because that is when the underlying is open and arbitrageurs are attentive.
- Chain and venue. The same economic exposure may exist on multiple chains with entirely separate, non-fungible liquidity pools.
Thin books mean your own order moves the price. For retail sizes this is usually negligible, and then occasionally it is not; specifically during the volatility that makes you want to trade.
When drift is worst
In rough order of severity:
- Weekends, particularly Saturday. Maximum time since the last real price, minimum participation.
- Immediately after earnings released post-close. The token repricing is a live wager on tomorrow's open, made in thin conditions. Gaps here can be large and are frequently wrong in both directions.
- During market-wide volatility while the underlying is closed. A macro shock on a Sunday sends every token searching for a level simultaneously, with no anchor.
- Holidays, especially multi-day closures. Longest possible gap between real prices.
- Thinly-traded names, always. For anything outside the largest tickers, drift is the baseline condition rather than an event.
Reading a discount correctly
A token trading below the last printed share price is not automatically a bargain. There are three distinct explanations and they demand opposite responses.
Explanation 1: the market is forecasting
The underlying is closed and participants expect it to open lower. The discount is information, and it is often approximately right. Buying it is not free money; it is taking the other side of a directional view.
Explanation 2: liquidity is temporarily absent
A large seller hit a thin book at an awkward hour. This genuinely does revert, and it is the closest thing to an opportunity in this list, but you need to be confident it is what you are looking at, which usually means knowing the flow.
Explanation 3: the market is repricing the issuer
This is the one that matters and the one people miss. Your token is a claim on an issuer. If the market develops doubts about that issuer's solvency, custody arrangements, or regulatory standing, the token deserves to trade below the value of the underlying share, and it will keep deserving it.
A persistent, widening discount across all of an issuer's tokens simultaneously is the signature of explanation 3. A discount in one ticker is a liquidity or forecasting story. A discount across the entire product line is a credit story, and the correct response to a credit story is not to buy more.
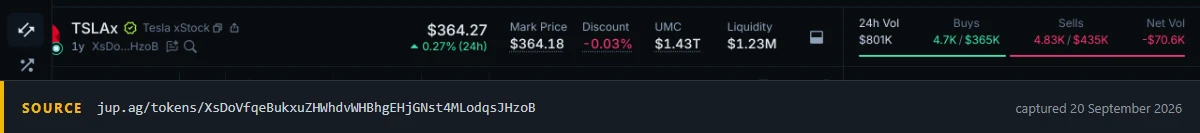
The discount field is drift with a number on it: traded price against the mark price the issuer quotes. Liquidity sits two columns over, and a thin pool is what turns a small gap into a large one.
How to measure it yourself
You need two numbers and a subtraction, but pay attention to the details.
-
Get the underlying's last real print, with its timestamp. Not a delayed quote, not a crypto aggregator's derived value.
-
Get the token's current mid-price: midpoint of bid and ask, not the last trade, which in a thin book might be hours stale and meaningless. On a centralised venue this is the order book on your own screen. For xStocks on Solana, where much of the trading happens against liquidity pools rather than a book, you can pull price and pool depth together without an account or an API key:
https://lite-api.jup.ag/tokens/v2/search?query=TSLAxThe fields to read are
usdPrice,liquidity(dollars of pooled liquidity behind the token) andstats24h. Swap in whichever ticker you hold. One warning that matters more than the price itself: that search returns every token using the symbol, and most of them are not the real one — checking that you are holding the genuine token explains how to tell them apart before you read any number off the wrong row. -
Compute the percentage difference and note how many hours have elapsed since the underlying's print.
-
Adjust for any pending rebase. If a dividend or split is being processed via balance adjustment, a raw price comparison is wrong. The underlying company's investor relations page carries its own dividend and split calendar, and that is the version to check against: a token's balance moves after the corporate action, so the raw price will look wrong for a window even when nothing is. Why your balance changes without a trade covers what that looks like when it happens to you.
Do this a few times across different hours for a ticker you follow and you will develop a feel for its normal drift band. That baseline is what makes an abnormal reading legible. Without it, every number looks like an opportunity.
We deliberately do not publish a drift table here. Any figure we printed would be stale within days, and a number you did not observe yourself is worthless as a baseline — the whole point is to know what your ticker does on your venue at your hours. Build it yourself: take four readings a week for a fortnight — one at the US open, one at the US close, one Saturday midday UTC, one Sunday evening UTC — and you will have a band that is actually yours. That the weekend gap is real and exploitable enough to attract arbitrage attention has been documented in market reporting; what has not been documented is what your specific position does, and that is the number you need.
Practical rules
- Use limit orders. Always. A market order into a thin book is how a 0.3% intended cost becomes 2%. This single habit matters more than everything else here.
- Prefer trading while the underlying market is open. Tighter spreads, active arbitrage, a real reference price. The 24/7 capability is valuable for reacting to news, but "I can trade now" and "I should trade now" are separate questions.
- Check depth before sizing, not after. Look at the book on both sides at your intended size. If your order is a visible fraction of it, split it or trade elsewhere.
- Treat weekend prices as opinions. They are frequently reasonable opinions. They are not prices in the sense you are used to.
- Watch for line-wide discounts. One ticker cheap is noise. Every ticker from the same issuer cheap at the same time is a signal about the issuer, and the right response is to reduce, not to buy the dip.
Drift is the price of the access these products give you, and in a jurisdiction where tokenised equities are your practical route to US market exposure, a few tens of basis points for that access is a reasonable trade. It stops being reasonable when you forget you are making it: when you compare your returns to the underlying's chart and wonder where the difference went, or when you read a weekend discount as a gift rather than a forecast.
Explanatory only; no recommendation is intended. Liquidity conditions and redemption arrangements change; verify current terms with the issuer.